Executive Summary & Direct Answer: The Fiduciary Standard for Special Committee Board Presentations
Key Institutional Takeaways for Special Committees & Independent Advisors
Simulate & Prototype: Special Committee Board Presentation Guide: Structuring Fiduciary Decks for Conflicted M&A, Take-Privates, and Fairness Opinions
Drag to draw custom components, test consulting layout presets, and preview presentation architecture live before generating with AI.
Table 1: Conflicted Transaction Typologies & Judicial Standards of Review in Board Decks
| Conflict Archetype | Transaction Structure & Parties | Default Judicial Standard | MFW / Safe Harbor Cleansing Path | Delegated Special Committee Mandate | Critical Board Deck Exhibits Required |
|---|---|---|---|---|---|
| Controlling Shareholder Take-Private / Squeeze-Out | Parent entity or controlling shareholder owning 30%-80%+ voting power acquires remaining public float for cash or securities | Entire Fairness (Fair Dealing + Fair Price review with defendant burden of proof) | Conditioned ab initio on independent Special Committee approval + Majority-of-Minority (MOM) uncoerced shareholder vote | Full power to review, negotiate, solicit third-party interest (if feasible), and reject proposal without parent retaliation | Sponsor offer vs standalone DCF valuation; negotiation progression waterfall; minority float liquidity and historical trading premiums |
| Management Buyout (MBO) with Rollover Equity | Executive leadership team (CEO, CFO, CTO) partners with a private equity sponsor, rolling equity and securing post-close equity incentive pools | Entire Fairness or Revlon enhanced scrutiny (direct economic conflict between rolling managers and cashed-out public common) | Early Special Committee formation prior to management employment or rollover negotiations; independent management projections audit | Exclusive authority to conduct market check, control management communication firewalls, and approve/reject sponsor transaction | Management incentive package benchmark; unaffected earnings sensitivity; pre-signing market check funnel; Go-Shop solicitation terms |
| Third-Party Strategic Merger with Disparate Consideration | Unaffiliated acquirer offers higher consideration, board seats, ongoing consulting fees, or commercial assets to controlling shareholder or founders | Entire Fairness due to divergent economic benefits received by fiduciaries not shared pro-rata with public common shareholders | Independent Special Committee negotiation of aggregate price and allocation of consideration; uncoerced MOM approval | Full power to negotiate consideration allocation; mandate to eliminate side deals or convert disparate benefits into pro-rata common cash | Allocation bridge comparing pro-rata value distribution; valuation of non-cash side benefits; relative contribution analysis |
| Related-Party Asset Sale / Joint Venture Formation | Company sells crown-jewel IP, operating subsidiary, or real estate assets to an affiliate, founder, or major director-affiliated entity | Entire Fairness under Delaware General Corporation Law (DGCL) Section 144(a)(1) safe harbors | Special Committee of disinterested directors evaluates asset valuation, alternatives, and independent fairness opinion | Power to hire independent industry technical experts and financial advisors to perform liquidation and replacement cost valuations | Sum-of-the-parts (SOTP) asset appraisal; arm’s-length transfer pricing comparison; tax leakage waterfall; impact on remaining core business |
| Unsolicited Takeover Bid with Hostile Defense / Poison Pill | Third-party hostile bidder launches tender offer; board evaluates defensive measures (Shareholder Rights Plan, staggered board) | Unocal enhanced scrutiny (directors must prove reasonable grounds for believing threat exists + defensive response is proportionate) | Special Committee formed if certain insiders have defensive conflicts or alternative management buyout aspirations | Mandate to evaluate bidder adequacy; manage poison pill trigger thresholds; explore white knight alternatives under Revlon | Bidder financial capacity and antitrust threat analysis; standalone value realization runway; pill pill redemption governance |
Exhibit 1: Special Committee Formation, Independence Charter & Legal Mandate Architecture
Independent Financial Valuation Frameworks: Structuring the Valuation Football Field
Exhibit 2: Independent Financial Advisor Valuation Summary & Football Field Range
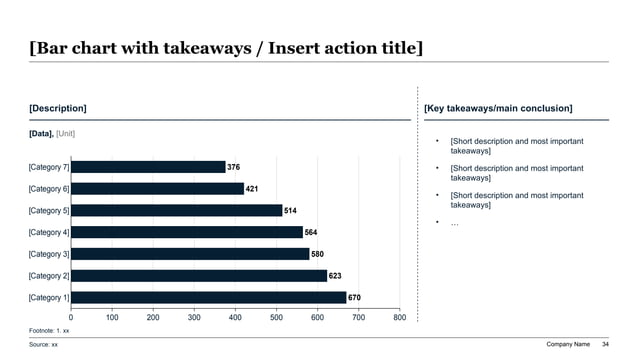
Table 2: Valuation Methodologies, Financial Inputs & Delaware Court of Chancery Scrutiny Matrix
| Valuation Methodology | Primary Financial Inputs & Multiples | Special Committee Sensitivity Focus | Common Valuation Vulnerabilities in Litigation | Chancery Court Scrutiny Precedents |
|---|---|---|---|---|
| Unlevered Discounted Cash Flow (Perpetuity Growth) | 5-10 year unlevered FCF; WACC (8.0%-10.5%); Terminal growth rate g (1.5%-2.5%) | Sensitivity of per-share equity value to $\pm 50$ bps WACC vs $\pm 25$ bps terminal growth; CapEx normalization | Management forecast manipulation; depressed out-year margin assumptions; arbitrary size premium add-backs to cost of equity | In re Trados Inc. S’holder Litig.; In re PetSmart, Inc.; Weinberger v. UOP, Inc. (mandating unmanipulated cash flow projections) |
| Unlevered Discounted Cash Flow (Exit Multiple) | 5-10 year unlevered FCF; WACC; Terminal EV/EBITDA multiple (8.0x-11.0x) | Alignment of exit multiple with long-term industry maturity; terminal year normalized working capital swings | Applying depressed exit multiples that imply negative terminal growth or double-counting cyclical trough earnings | In re Orchard Enterprises, Inc. (scrutinizing inconsistent terminal multiple selections between management and advisor decks) |
| Selected Public Comparable Companies | EV / NTM Revenue; EV / NTM EBITDA; P/E; Growth-adjusted EV/EBITDA/CAGR (PEG) | Peer set purity; excluding distressed outliers; adjusting for cash, minority interests, and capital structure leverage | Cherry-picking low-multiple legacy peers to depress the implied valuation corridor; ignoring high-growth pure-play peers | In re Nine Systems Corp. S’holder Litig. (rejecting comp sets hand-selected by conflicted fiduciaries to justify dilutive pricing) |
| Precedent M&A Transactions | Transaction EV / LTM EBITDA; Transaction EV / NTM EBITDA; 1-Day & 30-Day Unaffected Share Price Premiums (25%-45%) | Excluding distressed rescue sales; isolating transactions with public control premium data; distinguishing strategic vs financial deals | Mixing post-2022 high-interest-rate transaction comps with zero-interest-rate bubble transactions without macro reconciliation | In re PLX Technology Inc. S’holder Litig. (scrutinizing precedent transaction sample selection during activist-driven sales) |
| Leveraged Buyout (LBO) Ability-to-Pay | 4.5x-6.0x Debt / EBITDA; 18.0%-22.0% Sponsor Target IRR; 5-year exit multiple equal to entry or +1.0x expansion | Maximum equity sponsor check size; mezzanine debt availability; debt repayment sweeps; tax shield optimization | Treating the sponsor’s conservative internal return hurdle as the intrinsic corporate value ceiling rather than a pricing floor | In re Dole Food Co. Stockholder Litig. (penalizing management for sabotaging standalone projections to engineer an attractive sponsor LBO) |
| Sum-of-the-Parts (SOTP) / Segment Disaggregation | Segment standalone EBITDA; divisional peer multiples; corporate overhead allocation ($15M-$35M SG&A elimination) | Trapped cash at foreign subsidiaries; inter-company transfer pricing; stranded parent corporate overhead reallocation | Arbitrary corporate overhead allocations that artificially depress high-multiple business units; unverified tax liabilities | In re El Paso Corp. S’holder Litig. (scrutinizing SOTP valuation shifts where advisory conflicts influenced divisional multiple selection) |
Evaluating Strategic Alternatives: Standalone Status Quo vs. Active Market Check vs. Sale
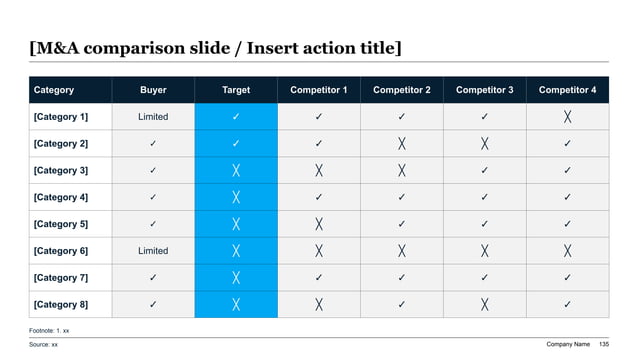
Exhibit 3: Strategic Alternatives Decision Matrix: Sponsor Offer vs. Standalone Plan vs. Strategic Merger
Negotiation Choreography: Documenting the Bilateral Offer-Counteroffer Record & Price Improvement Cascade
Exhibit 4: Bilateral Negotiation Chronology & Offer Improvement Cascade
The Fairness Opinion: Presentation Standards, Scope, Disclosure & Judicial Boundaries
Checklist 1: The Pre-Meeting Special Committee Fiduciary Readiness Gate (10 Mandatory Audits)
The 120-Day Special Committee Fiduciary Process Flight Path & Governance Sequence
Exhibit 5: The 120-Day Special Committee Fiduciary Flight Path & Governance Roadmap
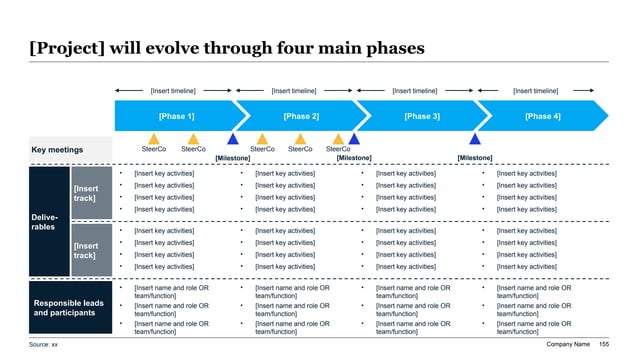
Table 4: Special Committee Board Presentation Blueprint (The 8-Section Master Deck Architecture)
| Deck Section | Slide Archetype & Format | Core Content & Financial Data | Lead Presenter & Role | Key Judicial Audit Purpose |
|---|---|---|---|---|
| 1. Executive Summary & Committee Recommendation | 3-Column Executive Card Layout with Key Takeaway Banner | Transaction headline terms ($53.50 cash); 27.4% premium; summary rationale; unanimous committee recommendation | Special Committee Chair | Establishes committee ownership of recommendation and arm’s-length independence |
| 2. Charter Mandate, Fiduciary Framework & Independence Record | Structured Text Matrix & Governance Hierarchy Diagram | Board charter powers; MFW ab initio compliance; director independence questionnaires; advisor engagement terms | Special Committee Independent Legal Counsel | Provides contemporaneous proof of Delaware procedural compliance and absence of fiduciary conflicts |
| 3. Standalone Business Plan & Market Reality Review | Multi-Year Financial Trajectory & Sensitivity Line/Bar Combo | Audited standalone 5-year projections; revenue CAGR (6.8%); CapEx requirements; operational risks and headwinds | Independent Financial Advisor / Management Interview Summary | Demonstrates that projections were stress-tested and unmanipulated by conflicted management |
| 4. Strategic Alternatives & Market Check Synthesis | 4-Column Comparison Matrix & Inbound Buyer Funnel | Standalone execution vs. third-party strategic sale vs. sponsor buyout; Go-Shop solicitation rights and fee tiers | Special Committee Financial Advisor | Proves fulfillment of Revlon / Unocal enhanced scrutiny duties to maximize shareholder value |
| 5. Independent Financial Valuation Analysis (Football Field) | Football Field Bar Chart + Detailed Sensitivity Tables | DCF ($48.00-$56.50); Public Comps ($44.00-$52.00); Precedent Transactions ($50.00-$58.00); LBO floor ($46.00-$51.50) | Senior Managing Director, Financial Advisory Firm | Establishes analytical foundation proving fairness of the $53.50 purchase price |
| 6. Negotiation Chronology & Merger Agreement Deal Terms | Sequential Cascade Waterfall & Non-Price Terms Table | Round-by-round bid progression ($42.00 to $53.50); MOM condition; 2.25% break fee; financing backstops | Special Committee Independent Legal Counsel | Memorializes aggressive price discovery and extraction of favorable non-price minority protections |
| 7. Shareholder Considerations & Regulatory Clearance Path | Pro-Forma Ownership & Regulatory Approval Flowchart | Unaffiliated shareholder voter intelligence; MOM pass probability; antitrust/HSR and CFIUS clearance timelines | Independent Legal Counsel & Proxy Advisory Specialist | Confirms that minority voting condition is uncoerced and closing certainty is legally secure |
| 8. Fairness Opinion Delivery & Formal Resolutions | Written Opinion Letter + Formal Legal Resolution Text | Delivery of oral and written Fairness Opinion; formal committee voting resolutions; proxy drafting timetable | Independent Financial Advisor & Committee Chair | Final formal certification of financial fairness and legal transaction authorization |
Checklist 2: The Final Transaction Approval & Board Presentation Verification Gate (10 Governance Checks)
XLSlides Special Committee Presentation Prompt Recipe
Role: Senior M&A Corporate Governance Partner & Independent Financial Advisor to Board Special Committees Task: Generate an institutional, decision-ready 18-slide Special Committee Board Presentation for independent directors evaluating a $1.85 billion conflicted take-private buyout proposed by a controlling private equity shareholder. Instructions: 1. Slide 1: Formal Confidential Title Slide featuring transaction headline, target company name, date, Special Committee independent designation, and strict attorney-client privilege legal disclaimers. 2. Slide 2: Executive Summary & Recommendation framing the $53.50/share all-cash offer (+27.4% premium over unaffected price), summary valuation ranges, and unanimous Special Committee recommendation. 3. Slide 3: Special Committee Mandate & Delaware Legal Framework articulating formal charter powers, advisor retention, and compliance with the MFW ab initio dual procedural safe harbors. 4. Slide 4: Director Independence & Advisor Conflict Certification documenting the substantive independence of all committee members and independent financial/legal advisor 24-month fee lookbacks. 5. Slide 5: Standalone Business Plan & Management Projection Audit presenting 5-year unmanipulated financial model ($420M to $585M revenue, EBITDA margin expansion from 22.4% to 26.8%) and operational risk sensitivities. 6. Slide 6: Independent Valuation Summary Football Field aligning Standalone DCF ($48.00-$56.50), Public Comps ($44.00-$52.00), Precedent Transactions ($50.00-$58.00), and LBO Floor ($46.00-$51.50) against the $53.50 offer price. 7. Slide 7: Unlevered Discounted Cash Flow (DCF) Deep-Dive presenting 5-year FCF build, WACC sensitivity matrix (8.0% to 10.5%), perpetuity growth rates (1.5% to 2.5%), and exit multiple terminal triangulations. 8. Slide 8: Selected Public Comparable Companies Benchmarking analyzing EV/NTM Revenue and EV/NTM EBITDA multiples across pure-play peer groups with growth/margin regression positioning. 9. Slide 9: Precedent M&A Transactions & Premiums Paid analyzing transaction multiples and 1-day/30-day unaffected control premiums in comparable strategic and sponsor buyouts. 10. Slide 10: Financial Sponsor LBO Ability-to-Pay Analysis calculating returns under 5.0x debt leverage and 20.0% target IRR to determine the sponsor's economic ceiling. 11. Slide 11: Strategic Alternatives Decision Matrix objectively comparing the $53.50 Cash Buyout vs. Standalone Plan vs. Third-Party Sale vs. Leveraged Recapitalization across certainty, value, and minority protection. 12. Slide 12: Pre-Signing Market Check & Go-Shop Architecture reviewing inbound bidder inquiries, the 35-day Go-Shop solicitation window, and the bifurcated 1.50% / 2.75% breakup fee structure. 13. Slide 13: Bilateral Negotiation Cascade Waterfall documenting round-by-round offer improvements from initial $42.00 indication to final $53.50 agreement (+$11.50/share, +$345M equity value). 14. Slide 14: Merger Agreement Non-Price Deal Terms & Minority Safeguards reviewing the non-waivable MOM closing condition, fiduciary out, matching rights, and hell-or-high-water regulatory covenants. 15. Slide 15: Financing Structure & Closing Certainty reviewing fully executed debt commitment letters, sponsor equity backstops, and 5.5% reverse termination fee with specific performance rights. 16. Slide 16: Independent Financial Advisor Fairness Opinion Summary outlining opinion scope, financial point-of-view certification, and disclosure of fee arrangements under SEC Schedule 13E-3. 17. Slide 17: Transaction Timeline & Regulatory Flight Path mapping the 90-day sequence from merger signing through antitrust clearance, SEC proxy review, shareholder vote, and closing. 18. Slide 18: Formal Committee Voting Resolutions & Legal Next Steps documenting formal adoption of Special Committee resolutions and recommendations to the full board of directors.