The Anatomy of an Executive Commercial Due Diligence Deck: Why Deals Die in Commercial Review
In middle-market and large-cap private equity transactions, financial due diligence (Quality of Earnings / QoE) tells the deal team where the target company has been, while commercial due diligence (CDD) determines whether the business will survive and compound over the next five-year holding period. A Quality of Earnings review inspects historical GAAP/IFRS revenue recognition, normalizes non-recurring expenses, and establishes the trailing-twelve-month (TTM) EBITDA peg. In contrast, commercial diligence stress-tests the future: Does the underlying market possess durable secular tailwinds or cyclical exposure? Is the target's customer base fiercely loyal or silently plotting migration to a modern alternative? Does the company have genuine pricing power, or is gross margin propped up by temporary vendor concessions? Most critically, is management's hockey-stick revenue forecast an achievable roadmap or a fantasy engineered to maximize the seller's valuation multiple?
When an Investment Committee (IC) rejects a proposed buyout or insists on a dramatic purchase price reduction during final exclusivity, the fatal flaw is rarely an accounting technicality. Deals fall apart in commercial review because the initial narrative fails to survive empirical cross-examination. A pitch deck may boast a $10 billion addressable market, but commercial diligence discovers the true serviceable niche is under $450 million with annual growth decelerating from 14% to 4%. A Confidential Information Memorandum (CIM) may celebrate a 98% gross customer retention rate, yet blinded customer interviews reveal that the target's flagship product suffers from an abysmal Net Promoter Score (NPS) of -18, with 30% of enterprise contract value actively evaluating competitor alternatives upon upcoming contract expiration. Without rigorous commercial diligence, sponsors risk underwriting multiple expansion and aggressive EBITDA growth on top of a commoditized asset facing imminent customer churn.
Top-tier management consulting firms—most notably Bain & Company, McKinsey & Company, The Boston Consulting Group (BCG), EY-Parthenon, and L.E.K. Consulting—have refined commercial due diligence into an exacting, high-velocity science. Operating under compressed three-to-four-week exclusivity sprints, CDD teams ingest vendor data rooms, build bottom-up addressable market models, scrape competitive pricing and product telemetry, conduct 30 to 50 blinded customer and competitor executive interviews, and reconstruct billing ledgers down to the individual customer cohort. The resulting presentation is not a meandering research memo; it is an executive decision document designed to withstand intense scrutiny from seasoned private equity partners, co-investors, and credit committee lenders.
To satisfy this executive bar, an institutional CDD presentation must answer four existential questions with quantitative finality: (1) Market Realities: Is the target operating in an expanding, resilient pool of profit, and what macroeconomic or technological shifts could compress market growth? (2) Moat Defensibility: Does the business possess structural competitive advantages—such as high switching costs, proprietary data network effects, or embedded operational workflows—that protect market share and unit margins against aggressive incumbents and venture-backed point solutions? (3) Voice of Customer (VoC): Do customers view the target as a critical, mission-critical 'painkiller' or a discretionary 'vitamin', and what is their empirical willingness to absorb regular 5-10% price increases? (4) Forecast Haircutting: Exactly how much must management's budget be haircut across sales rep productivity, churn normalization, and delayed product releases to construct an underwritten base case that protects the fund's downside return hurdle?
This guide breaks down the core architecture, slide-by-slide frameworks, analytical tables, visual exhibits, and review workflows required to build a board-grade commercial due diligence deck that commands credibility in the boardroom, equips deal partners to negotiate purchase price adjustments, and lays the analytical foundation for the post-acquisition 100-Day Value Creation Plan.
Executive Summary & Core Commercial Diligence Takeaways
- Triangulate TAM from the Bottom Up: Reject passive top-down syndicated research numbers. Construct bottom-up market sizing by multiplying qualified target accounts by empirically verified Annual Contract Value (ACV) tiers across discrete buyer segments.
- Disaggregate Retention Into Cohorts: Never accept aggregate renewal metrics at face value. Reconstruct vintage cohort decay curves to isolate Gross Revenue Retention (GRR), Net Revenue Retention (NRR), and logo churn, confirming that top-line growth is not masking structural customer attrition.
- Benchmark Moats Beyond Feature Checklists: Evaluate competitive defensibility through switching friction, integration depth into client ERP/core workflows, pricing realization track records, and win/loss velocity—not subjective marketing matrices.
- Rigorously Execute Blinded VoC Campaigns: Conduct 25 to 45 blinded primary interviews across promoters, neutrals, churned former clients, and competitor accounts to quantify genuine Net Promoter Score (NPS), purchasing criteria satisfaction, and price increase tolerance.
- Bridge the Management Forecast Haircut: Build a transparent bridge from Management's CIM forecast to the Underwritten Base Case, quantifying dollar-for-dollar haircuts for sales capacity bottlenecks, delayed product cycles, and churn cliffs.
- Enforce Action Title Discipline: Every slide in the CDD deck must feature a concise, quantitative action title that synthesizes the finding, the empirical proof, and the investment consequence—eliminating passive topical headings.
Exhibit 1: Market Sizing, Historical Growth, and Segmented CAGR Trajectory
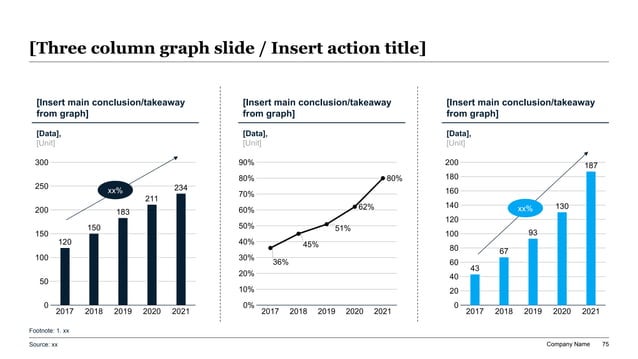
TAM, SAM, and SOM Architecture: Triangulating Market Realities and Growth Vectors
The most pervasive vulnerability in sponsor presentations is an inflated, poorly bounded addressable market. Target management teams routinely insert slides citing multi-billion-dollar figures sourced from third-party syndicated research houses (e.g., Gartner, IDC, Statista). While these macro figures sound impressive to passive observers, sophisticated private equity investment committees view unadjusted macro numbers as a red flag. A $15 billion global logistics software market is entirely irrelevant if the target company sells a localized dispatch tool tailored exclusively to independent refrigerated trucking fleets with 10 to 50 vehicles—a sub-segment whose true addressable spend may barely reach $380 million.
Commercial diligence demands a rigorous tripartite market architecture: Total Addressable Market (TAM), Serviceable Addressable Market (SAM), and Serviceable Obtainable Market (SOM). TAM represents the total theoretical annual spend if 100% of potential buyers globally adopted the solution category. SAM refines this universe by applying realistic qualification filters: geographic territories where the target operates, regulatory compliance boundaries, technical infrastructure prerequisites, and enterprise size bands. SOM represents the realistic market share the target can capture over the fund's five-year investment horizon given sales capacity constraints, competitive displacement barriers, and brand awareness limitations.
To achieve institutional credibility, the CDD team must triangulate market size through two independent methodologies: Top-Down Spend Filtering and Bottom-Up Account Aggregation. Top-down analysis starts with broad industry revenue and systematically applies defensible haircut percentages to isolate the target's exact addressable budget category. Bottom-up analysis begins at the company level: the team queries firmographic databases (e.g., Dun & Bradstreet, ZoomInfo, proprietary registry filings) to establish an exhaustive count of qualified target entities stratified into enterprise tiers (e.g., Tier 1 Enterprise: 5,000+ employees; Tier 2 Mid-Market: 500-4,999 employees; Tier 3 SMB: 50-499 employees). Each tier is then multiplied by empirical, realized Annual Contract Value (ACV) figures derived from the target's anonymized transaction logs.
When top-down and bottom-up analyses converge within a 10% to 15% variance corridor, the investment committee gains high confidence in the market sizing baseline. Furthermore, the CDD deck must decompose market growth into three distinct vectors: (1) Underlying Industry Volume Growth (macro economic expansion of the target customer base), (2) Secular Penetration & Adoption Tailwind (the rate at which manual spreadsheets or legacy on-premise systems are displaced by modern software), and (3) Annual Price Realization (the historical and forward ability of vendors to push CPI or value-based price increases). Deconstructing market CAGR into these constituent levers proves whether the target is riding an inevitable structural wave or fighting a brutal zero-sum market share battle.
Market Sizing Methodology & Diligence Verification Matrix
Comparison of market sizing approaches deployed during commercial due diligence, data sources required, vulnerability to sponsor skepticism, and IC verification standards.
| Sizing Approach | Calculation Methodology | Primary Data Sources | Common Vulnerabilities & Blindspots | Investment Committee Diligence Standard |
|---|---|---|---|---|
| Top-Down Macro Sizing | Global industry spend filtered by geographic, enterprise tier, and product category percentage splits. | Gartner, IDC, Forrester, Statista, trade associations, SEC filings. | Overestimates addressable spend by bundling non-discretionary or non-substitutable legacy solutions. | Permissible only as macro context; rejected by PE ICs if used as the primary basis for revenue underwriting. |
| Bottom-Up Account Triangulation | Total universe of qualified business accounts (by employee count, revenue, IT spend) multiplied by realized target ACV. | Dun & Bradstreet, ZoomInfo, proprietary expert calls, company CRM log analysis, customer billing records. | Risk of double-counting enterprise subsidiaries or assuming uniform ACV across disparate buyer segments. | Gold standard for IC deal decks; requires disaggregated ACV tiers by customer size and geographic region. |
| Value-Pool & Spend Displacement | Quantifies the total budget pool currently spent on manual labor, legacy on-premise software, or outsourced agencies that the target displaces. | Customer CFO interviews, process time-and-motion studies, salary benchmarks, procurement disclosures. | Fails if switching inertia or internal resistance prevents budget reallocation from operational cost centers. | Required when underwriting disruptive market entrants creating a new software or workflow category. |
| Capacity & Throughput Boundary Sizing | Quantifies maximum operational or transaction throughput capacity multiplied by fee per unit transaction. | Production line audits, server utilization metrics, regulatory capacity permits, supply chain constraints. | Ignores price elasticity and assumes linear utilization growth without incremental marginal CapEx. | Crucial for asset-heavy, logistics, healthcare facility, or infrastructure-adjacent buyout targets. |
Exhibit 2: Relative Competitive Positioning Matrix & Market Share Dynamics
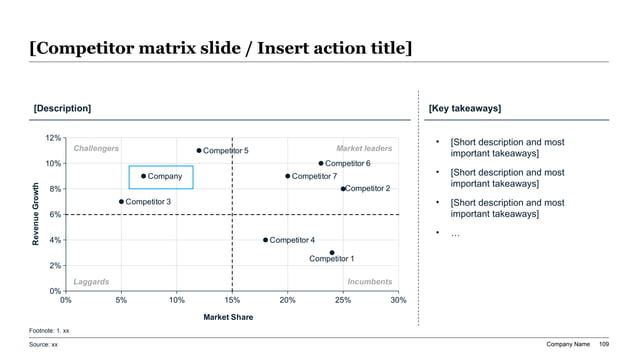
5-Competitor Moat Assessment & Competitive Displacement Matrix
Detailed competitive evaluation framework comparing target performance against direct peers across product architecture, pricing power, customer switching friction, and vulnerability.
| Competitor Profile | Market Share & Trajectory | Core Moat & Architecture | Pricing Power & Realization | Competitive Vulnerability / Deal Risk |
|---|---|---|---|---|
| Target Company (Acquisition Candidate) | 14% market share; expanding at 2.4x market CAGR via mid-market displacement. | Native cloud architecture, deep workflow integration into core ERPs, proprietary industry workflow templates. | Strong: 8-12% annual price increases realized on contract renewals with negligible churn elasticity. | Relies heavily on founder-led enterprise sales; lower international footprint compared to Tier-1 global players. |
| Legacy Incumbent A (Tier-1 Conglomerate) | 38% market share; contracting at -2% YoY due to technical debt and platform fatigue. | Decades of on-premise installation, enterprise procurement relationships, bundled multi-product enterprise licenses. | Weak: Forced to discount up to 40% on renewals to combat customer churn to modern cloud solutions. | Monolithic code base, agonizing 18-month implementation cycles, poor NPS ratings (-12) among end-users. |
| Modern Point-Solution B (VC-Backed) | 9% market share; rapid top-line growth fueled by aggressive venture-subsidized discounting. | Slick modern UI/UX, fast self-serve onboarding, specialized single-workflow automated feature set. | Negative: Heavy discounting, negative gross margins on custom onboarding, high logo churn at year two. | Lacks enterprise governance, SOC2 Type II compliance, and robust API connectivity; faces cash runway pressure. |
| Enterprise Suite Competitor C | 22% market share; stable market share focused on Global 2000 multinational accounts. | Extensive global support footprint, multinational multi-currency compliance, bundled ERP suite discounts. | Moderate: Standard CPI inflation escalators; pricing power tied to master service agreements. | High total cost of ownership (TCO), lack of vertical industry specialization, rigid configuration constraints. |
| Low-Cost Emerging Competitor D | 6% market share; gaining ground in entry-level, price-sensitive SMB tiers. | Offshore engineering, aggressive low-cost pricing model, basic feature parity for core utilitarian workflows. | Zero pricing power: competes purely on price per seat; vulnerable to platform feature commoditization. | High customer support burden, security vulnerabilities, zero presence in enterprise RFPs with strict audit requirements. |
Exhibit 3: Comprehensive 5-Competitor Moat & Feature Benchmark Matrix (Harvey Balls)
Voice of Customer (VoC): Cohorts, Churn, and Pricing Power Validation
In private equity diligence, blinded customer interviews represent the crucible of truth. While target founders and management teams can present polished pitch slides and hand-pick supportive customer references, blinded primary research bypasses corporate public relations to uncover operational reality. An elite commercial due diligence team conducts 25 to 45 structured interviews spanning four distinct interviewee cohorts: (1) Current Core Customers (high-volume accounts representing core run-rate revenue), (2) At-Risk or Downsized Accounts (clients whose usage or seat count declined over the past 12 months), (3) Churned / Former Customers (organizations that terminated contracts within the last 24 months), and (4) Competitor Customers (buyers who evaluated the target during an RFP process but selected a rival platform).
The primary objective of customer diligence is to quantify three critical performance metrics that dictate the company's valuation: Net Promoter Score (NPS), Customer Lifetime Value to Acquisition Cost (LTV/CAC) sustainability, and Cohort Retention Stability. Headline revenue growth often obscures dangerous underlying churn. For instance, a SaaS company growing revenue by 28% annually may appear healthy on an income statement; however, cohort analysis may reveal that 22% of gross customer accounts churn every year, with the deficit masked by aggressive, expensive outbound sales. In private equity, high-churn businesses suffer multiple compression because the buyer is forced to spend massive capital simply refilling a leaking bucket before generating incremental growth.
To rigorously diagnose customer retention, the CDD team constructs Longitudinal Vintage Cohort Decay Curves. Using raw transaction-level billing data from the target's ERP or billing gateway (e.g., Stripe, NetSuite, Salesforce), the team tracks customer groups segmented by acquisition year (e.g., 2021 Cohort, 2022 Cohort, 2023 Cohort, 2024 Cohort) across successive quarters. This disaggregates revenue into Gross Revenue Retention (GRR: retention excluding upsells and expansions, which should exceed 88% to 92% for healthy enterprise B2B software) and Net Revenue Retention (NRR: retention including upsell, cross-sell, and pricing increases, which should ideally exceed 110% to 125%).
Equally vital is empirical testing of Pricing Power and Headroom. In inflationary or rate-tightening environments, PE sponsors cannot rely on multiple expansion; equity returns must be driven by organic EBITDA expansion. During customer interviews, the CDD team deploys Van Westendorp Price Sensitivity and Gabor-Granger willingness-to-pay questioning: At what price would the product become too expensive to consider? At what price would you consider it a bargain? If the software increased in price by 10% on your next contract renewal, would you pay it, attempt to negotiate, or issue an RFP to switch vendors? When 80%+ of customers report that a 10% price bump would be accepted without executive escalation due to high switching friction and essential daily utility, the sponsor gains rock-solid confidence in underwriting post-closing price optimization levers.
Exhibit 4: Voice of Customer (VoC) Journey & Purchasing Criteria Satisfaction Matrix
Blinded Customer Due Diligence & Churn Verification Checklist
Stress-Testing the Target Management Case: The Diligence Haircut Framework
The Confidential Information Memorandum (CIM) distributed by investment bankers in an M&A auction is an inherently promotional sales document. The financial projections prepared by management invariably depict an 'up-and-to-the-right' acceleration: revenue growth rates that double, gross margins that expand without incremental CapEx, and sales quotas that are achieved with clockwork perfection. Underwriting an LBO (leveraged buyout) model using management's unadjusted CIM projections is the fastest way for a private equity associate to destroy fund capital and compromise their career.
The core deliverable of commercial due diligence is the Diligence Haircut Bridge: a transparent, quantitatively rigorous bridge that reconciles Management's CIM Forecast down to the Underwritten Base Case and the Downside Stress Case. The CDD team systematically reviews each operational growth driver, compares management's assumptions against historical empirical baselines and industry benchmarks, and deducts defensible dollar haircuts for ungrounded optimism.
The five standard haircut categories applied during commercial due diligence include: (1) Sales Rep Ramp-Up Delay: Management often models newly hired Account Executives (AEs) reaching full quota productivity within 90 days. Empirical CRM pipeline audits typically show that median ramp-up timelines require 6 to 9 months, creating a substantial revenue lag. (2) Churn Normalization: If historical gross churn averaged 11% but management projects churn dropping to 5% based on future 'customer success investments', the CDD team normalizes churn back to empirical reality. (3) Pipeline Conversion Realism: Discounting early-stage pipeline opportunities that have not passed technical validation or procurement gating. (4) Unreleased Product Deferral: Deducting 50% to 100% of modeled revenue from unbuilt software features or uncertified product lines whose release dates are vulnerable to engineering delays. (5) Pricing Elasticity Haircut: Capping aggressive price increases if VoC interviews indicate buyer pushback.
When presented to the Investment Committee, the Haircut Bridge demonstrates intellectual honesty and analytical rigor. Rather than dismissing management's vision out of hand, the CDD deck clearly articulates: 'Management projects $68.0 million in Year 3 revenue. Our diligence underwrites $48.5 million in Year 3 Base Case revenue and $39.2 million in Downside Case revenue. At the current offer price, the investment achieves a 22.4% Net IRR in the Underwritten Base Case and a 14.8% IRR in the Downside Stress Case, satisfying the fund's 18% hurdle rate while providing an asymmetric margin of safety.'
Management Case vs. Diligence Base Case Bridge & Haircut Rationale
Detailed waterfall bridge quantifying the specific adjustments, operational rationale, and EBITDA impact transforming Management's CIM forecast into the Underwritten Base Case.
| Revenue / Growth Driver | Management Case Forecast | Diligence Finding / Reality Check | Recommended Haircut Adjustment | Underwritten Base Case Impact |
|---|---|---|---|---|
| Core Account Expansion (NRR) | 125% NRR sustained across all cohorts via aggressive cross-sell of new modules. | Historical NRR averaged 108%; cross-sell adoption is slowing as core customers reach budget caps. | Haircut NRR assumption to 110% in Year 1, decaying to 106% steady-state by Year 3. | -$4.8M revenue deduction by Year 3; preserves high-confidence baseline expansion. |
| New Logo Sales Quota Productivity | $1.2M ARR quota capacity per Account Executive with a 3-month ramp-up cycle. | CRM audit indicates median AE productivity is $780k with an actual ramp-up period of 6.5 months. | Haircut quota productivity by 25% and extend assumed AE ramp-up timeline to 7 months. | -$6.2M revenue deduction; prevents underwriting unrealistic sales team velocity. |
| Unreleased Enterprise Product V2 | $8.5M revenue contribution modeled from unreleased automated compliance module. | Engineering interviews reveal development is 4 months behind schedule with beta testing unstarted. | Haircut Year 1 contribution by 100% and delay commercial launch assumption by 12 months. | -$3.5M Year 1 revenue; resets launch timeline to Q3 of Year 2. |
| Gross Logo Churn Rate | Assumes annual logo churn drops from 9% historical to 4% due to new customer success hire. | Customer interviews reveal upcoming ERP migration will trigger RFP reviews in 15% of accounts. | Increase modeled churn from 4% to 8.5%, factoring in customer contract renewal cliffs. | -$2.9M revenue impact; cushions against macro IT budget rationalization. |
| Pricing Power Realization | Assumes blanket 15% price increase across the installed customer base on renewal. | VoC calls show mid-market accounts have tight budgets; only 6-8% increase is feasible without churn. | Haircut price increase assumption to 7% with a 1.5% associated logo churn penalty. | -$2.1M revenue impact; aligns pricing strategy with empirical customer willingness-to-pay. |
| Total Underwritten Variance | $68.0M Year 3 Revenue / $22.4M EBITDA | Management plan relies on five simultaneous upside outcomes with zero margin for error. | Cumulative -$19.5M Revenue Haircut / -$7.8M EBITDA Haircut across 5 workstreams. | $48.5M Year 3 Revenue / $14.6M Underwritten Base Case EBITDA (IC Approval Baseline) |
Exhibit 5: Diligence Haircut Waterfall: Bridge from Management Plan to Underwritten Base Case
The 48-Hour Pre-Investment Committee CDD Red Flag Checklist
Transforming Raw Diligence Data into Board-Grade Slide Visuals with XLSlides
Commercial due diligence is characterized by extreme time compression. Consulting teams and private equity deal associates typically have between 14 and 28 calendar days to ingest gigabytes of virtual data room documents, conduct 35+ customer and industry expert calls, clean and merge hundreds of thousands of ERP billing lines, stress-test complex LBO financial models, and compile an 80-to-100-slide presentation for the fund's Investment Committee.
In traditional advisory workflows, an enormous proportion of associate bandwidth is consumed by low-leverage mechanical slide production: manually drawing shape boxes in PowerPoint, aligning Harvey Ball circles, color-coding data tables, reformatting chart legends, and debugging broken slide masters at 3:00 AM. This manual overhead steals precious hours away from deep analytical inquiry, sensitivity modeling, and partner-level deal synthesis.
XLSlides re-engineers this workflow by providing an AI-native presentation engine built specifically for serious business, finance, and strategy decks. Rather than generating generic, artistic slides with irrelevant stock illustrations and superficial bullet points, XLSlides understands the architectural discipline of executive presentations: MECE issue trees, answer-first action titles, clean multi-column container layouts, quantitative data tables, structured Harvey Ball scorecards, and verifiable source citations.
Deal teams can ingest raw customer interview transcripts, market sizing data tables, and management variance schedules directly into XLSlides. The engine automatically synthesizes findings into native, fully editable Microsoft PowerPoint (.pptx) presentation decks adhering to the visual standards of McKinsey, Bain, and elite private equity firms. Analysts and associates retain 100% control to edit typography, adjust financial haircut numbers, swap exhibit layouts, and brand slides with firm-specific color palettes—slashing deck generation turnaround from days to minutes while elevating final output quality.
Commercial Diligence Slide Generation Prompt Recipe
Act as a Senior Private Equity Commercial Due Diligence Principal at an elite strategy consultancy (Bain, McKinsey, L.E.K.). Build a comprehensive, 6-slide Commercial Due Diligence executive summary module evaluating [Target Company Name], a B2B SaaS provider generating $32M ARR in the [Sector Name] market. Data inputs: - Market: Total Addressable Market (TAM) is $4.2B growing at 9.5% CAGR, driven by regulatory compliance mandates and workflow automation. SAM is $1.1B. - Competitive Landscape: Target holds 12% market share (expanding at 22% YoY), competing against an incumbent losing share (42% share, -3% YoY) and 3 venture-backed point solutions. - Voice of Customer (VoC): 32 blinded interviews reveal an NPS of +48, 108% NRR, 92% GRR, with top purchasing criteria being ERP integration speed and ease of compliance reporting. - Management Case Haircut: Management models $65M ARR in 3 years; diligence haircuts new logo acquisition by 20% and delays Product V2 launch by 9 months, yielding an Underwritten Base Case of $49M ARR. Generate the following 6 slides with precise consulting structure: Slide 1: Executive Verdict & Diligence Summary (Answer-first recommendation, key deal drivers, critical risks, and valuation impact). Slide 2: Market Sizing & Segmented Growth Waterfall (TAM/SAM/SOM breakdown, historical CAGR, and 5-year secular expansion vectors). Slide 3: Competitive Landscape & Moat Matrix (Harvey Ball evaluation across 5 peers covering product depth, enterprise readiness, and pricing power). Slide 4: Blinded Voice of Customer (VoC) Scorecard (NPS distribution, purchasing criteria satisfaction curves, and cohort retention decay). Slide 5: Management Case vs. Diligence Base Case Bridge (Waterfall table bridging Management CIM forecast to Underwritten Base Case across 5 haircut levers). Slide 6: Key Diligence Findings & 100-Day Value Creation Levers (Pricing optimization, go-to-market acceleration, and cross-sell expansion priorities). Formatting requirements: Every slide must have a quantitative action title stating the conclusion, structured 2-column or 3-column container layouts, bulleted evidence points with bold lead-ins, and an explicit source footnote (e.g., 'Source: XLSlides CDD Analysis, 32 Blinded Customer Interviews, Company CRM Billing Records').
Governance, Deal Team Review Workflows, and Investment Committee Readiness
The ultimate test of a commercial due diligence presentation is how it performs in the Investment Committee (IC) meeting when deal partners, investment committee chairs, and external senior advisors cross-examine the deal team. A successful IC presentation is not an informational lecture; it is a structured debate aimed at stress-testing downside capital risk, evaluating upside asymmetry, and approving or rejecting the binding transaction terms.
To ensure seamless IC execution, elite advisory teams adhere to the 'No Surprises' protocol. Throughout the four-week diligence sprint, the CDD lead schedules weekly 30-minute touchpoint check-ins with the deal team partner. Critical red flags—such as severe customer churn in an anchor account, delayed product beta tests, or emerging regulatory hurdles—are socialized immediately upon discovery. When the final deck is delivered, the deal team should already be familiar with every major negative finding and possess a clear plan to incorporate it into purchase price negotiations, indemnity escrows, or management earnouts.
Another vital structural discipline is Appendix Architecture. The main presentation delivered to the Investment Committee should be lean and punchy—typically 20 to 30 core decision slides that can be reviewed in 45 minutes. However, the comprehensive deliverable should feature an exhaustive, meticulously organized Appendix spanning 50 to 80 supporting slides. The appendix must house full blinded customer call summaries, raw cohort retention decay schedules, econometric regression models, competitor patent teardowns, and regional TAM calculation spreadsheets. When an IC member challenges a specific churn assumption, the deal team can instantly navigate to the exact supporting exhibit in the appendix, demonstrating unassailable analytical thoroughness.
Finally, commercial diligence must not terminate upon transaction closing. In modern private equity, the CDD deck serves as the foundational operating blueprint for the 100-Day Post-Acquisition Value Creation Plan (VCP). The customer satisfaction gaps, pricing realization opportunities, sales territory bottlenecks, and product roadmap priorities uncovered during commercial diligence are directly handed over to the incoming CEO and PE Operating Partners to drive rapid, focused operational execution from Day 1.
Frequently Asked Questions About Commercial Due Diligence Decks
What is the primary purpose of a commercial due diligence (CDD) presentation?
The primary purpose of a CDD presentation is to provide private equity investment committees, corporate M&A boards, and lenders with an objective, independent assessment of an acquisition target's market environment, competitive moats, customer relationships, and revenue durability. Unlike financial diligence (Quality of Earnings), which evaluates historical accounting numbers, CDD validates future growth potential and stress-tests management's financial forecasts.
How long is a typical commercial due diligence presentation?
A comprehensive CDD presentation typically spans 50 to 90 slides. However, the executive summary section presented to the Investment Committee or Board is usually condensed to 15 to 25 core decision slides, with the remaining 40 to 65 slides organized in thematic appendixes covering raw interview transcripts, market model sensitivity tables, competitor product teardowns, and regional cohort data.
What is the difference between top-down and bottom-up market sizing in CDD?
Top-down market sizing takes global or national industry expenditure from secondary research reports and applies filters (geography, segment, company size) to estimate addressable spend. Bottom-up market sizing identifies the exact number of potential target accounts across defined enterprise tiers and multiplies that universe by the target's empirical Annual Contract Value (ACV). PE investment committees strongly favor bottom-up sizing because it eliminates theoretical spend and reflects actionable market reality.
How many customer interviews should be conducted during commercial due diligence?
Most PE commercial diligence studies conduct 25 to 45 blinded primary interviews during a standard 3-to-4 week diligence window. A balanced sample should include 15 to 25 current customers across various size tiers, 6 to 10 churned or former customers to diagnose loss drivers, and 6 to 10 competitor customers to benchmark rival product perceptions and switching friction.
What is a diligence haircut in M&A presentations?
A diligence haircut is a downward adjustment made by the diligence advisory team to management's financial forecast in the Confidential Information Memorandum (CIM). Common haircut categories include delaying sales representative quota productivity, capping optimistic Net Revenue Retention (NRR) expansion, extending the development timeline for unreleased products, and factoring in empirical customer churn cliffs.
How does XLSlides help teams create commercial due diligence decks?
XLSlides allows strategy consultants, PE associates, and corporate development leads to transform raw diligence findings, customer interview notes, and financial models into institutional, board-grade PowerPoint slides in minutes. The platform enforces consulting-grade visual layouts, action titles, MECE logic, and full slide editability in native Microsoft PowerPoint (.pptx).
Build Investment Committee-Ready Commercial Diligence Decks Faster
Stop spending late nights wrestling with PowerPoint shape alignment and manual Harvey Balls. XLSlides equips strategy consultants and private equity deal teams to convert raw diligence findings, market models, and customer interviews into executive-ready slides with institutional layout discipline, MECE structure, and full PowerPoint editability.
Generate Your CDD DeckMethodology And Sources
- Bain & Company Global Private Equity Report (Deal Diligence & Value Creation)
- McKinsey & Company Strategy & Corporate Finance Insights on M&A Due Diligence
- Harvard Business Review: The New M&A Playbook (Why Commercial Diligence Matters)
- CFA Institute: Private Equity Deal Sourcing and Diligence Standards
- L.E.K. Consulting: Strategic Market Reviews & Commercial Diligence Methodology